Mr. Gnansekhar
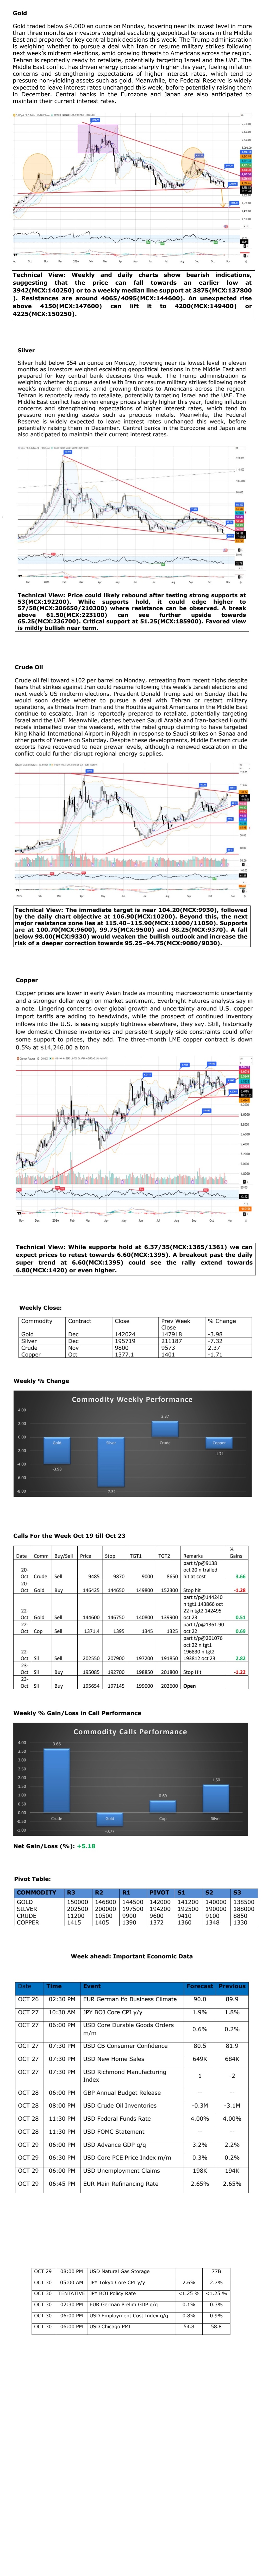
Teaser: Gold sank to a three-month low on Friday, on track for its worst weekly
decline in over four months, as rising energy costs fuelled inflation fears and
strengthened US rate hike predictions ahead of next week's Federal Reserve meeting.
Brent crude reached a more than five-month high after Houthi strikes in Saudi Arabia
fuelled concerns about additional disruptions to energy supply. Meanwhile, markets
expect the Fed to keep interest rates steady at its meeting on October 27-28, despite
stronger-than-expected US consumer and producer inflation statistics reported last
week, which boosted the case for tighter monetary policy later this year.
Introduction:
Gold and silver remain vulnerable to monetary policy uncertainty following
substantial selling pressure, with gold retreating towards $4,000/oz and silver
towards $54/oz. Elevated crude prices have revived inflation concerns, reinforcing
expectations of restrictive US interest rates despite softer Treasury yields. The
Federal Reserve's October 28 decision remains central, with markets
anticipating unchanged rates but closely assessing Chairman Warsh's
guidance on December policy. US GDP, PCE inflation and employment cost data
could significantly influence real yields and dollar movements. Gold retains underlying
support from geopolitical uncertainty and central bank demand, although liquidation
risks persist. Silver faces additional pressure from speculative positioning and
industrial demand sensitivity. Softer inflation readings could encourage recovery,
while hawkish guidance may extend selling pressure. WTI crude faces heightened
volatility after advancing to $103.27/barrel, supported by escalating Houthi attacks
against Saudi energy infrastructure and renewed maritime security concerns. Brent's
advance above $116/barrel reflects persistent geopolitical supply premiums, while
disruptions near the UAE and reduced Libyan production have added uncertainty.
However, recovering Persian Gulf exports and resumed Russian diesel shipments
could partially offset immediate supply risks. Emergency petroleum reserve releases
provide additional flexibility, although their scale remains limited relative to broader
consumption. Attention will center on US-Iran diplomatic developments, potential
attacks on regional infrastructure, Russian refinery disruptions and EIA inventory
figures. The Federal Reserve's policy decision and incoming inflation data could
influence dollar strength and demand expectations. Further disruptions may sustain
premiums despite improving export availability.