Mr. Gnansekhar
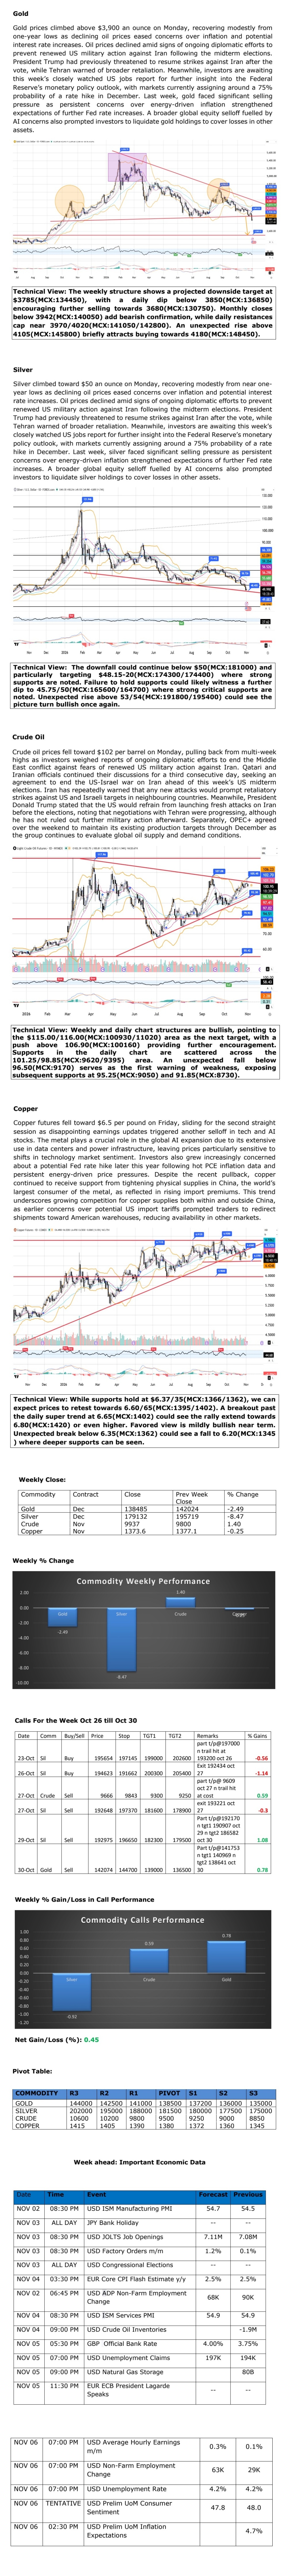
Teaser: The price of gold futures fell to the lowest in over a year on Friday and silver
dropped below $50/oz for the first time since last November, as wars in the Middle
East and Russia-Ukraine push oil prices higher, raising inflation concerns with
implications of higher interest rates. Following another tanker raid in the Strait of
Hormuz, crude oil prices surged more than 2%, heightening concerns about inflation
and raising predictions that U.S. Federal Reserve policy will continue to be restrictive.
As consumers paid more for petrol and other products in September, U.S. inflation
increased, supporting experts' predictions of a rate hike in December. The steep drop
in tech stocks, with the tech-heavy Masdaq falling by about 3%, may have
contributed to the slide in precious metals as well. This could have resulted in forced
selling and margin calls.
Introduction:
Gold and silver remain vulnerable to monetary policy uncertainty following
substantial liquidation triggered by technology equity losses and margin-related
selling. Stronger US economic growth and elevated PCE inflation reinforced
expectations of further Federal Reserve tightening, increasing the opportunity cost of
holding non-yielding assets. However, easing crude prices could moderate energy
driven inflation concerns and provide support through softer real yields. Friday's US
employment report will be crucial in shaping December rate expectations, while
manufacturing and services PMI readings could influence dollar movements. The US
midterm elections and renewed diplomatic engagement with Iran introduce additional
geopolitical uncertainty. Crude oil remains exposed to competing geopolitical and
supply developments as renewed US-Iran diplomatic efforts raise expectations of de
escalation, while threats against Middle Eastern energy infrastructure sustain supply
disruption risks. Houthi claims of attacks on Saudi facilities and reports of maritime
incidents near the Strait of Hormuz have heightened concerns over regional shipping
security, although several incidents remain unconfirmed. Meanwhile, recovering
Russian refinery operations and improving Persian Gulf export availability could ease
immediate supply constraints. Planned US Strategic Petroleum Reserve
replenishment may provide incremental demand support, partially offsetting
recovering production. Developments surrounding the US midterm elections could
influence Washington's approach towards Iran, while EIA inventory figures will clarify
near-term supply conditions. US employment data and dollar movements could
further affect demand expectations and speculative positioning.